
Should You Raise Your Car Insurance Deductible?
Everyone wants a lower auto insurance bill. Rates have climbed for years. So many drivers decide to raise their car insurance deductible.
It feels like an easy win. You take on more risk, and the premium drops.
But does it actually drop? In most cases, not by much. Sometimes the savings are so small they are hard to justify.
A Real Quote: Should He Raise His Car Insurance Deductible?
I quoted a client this week. His six-month premium was about $1,150 for his vehicle.
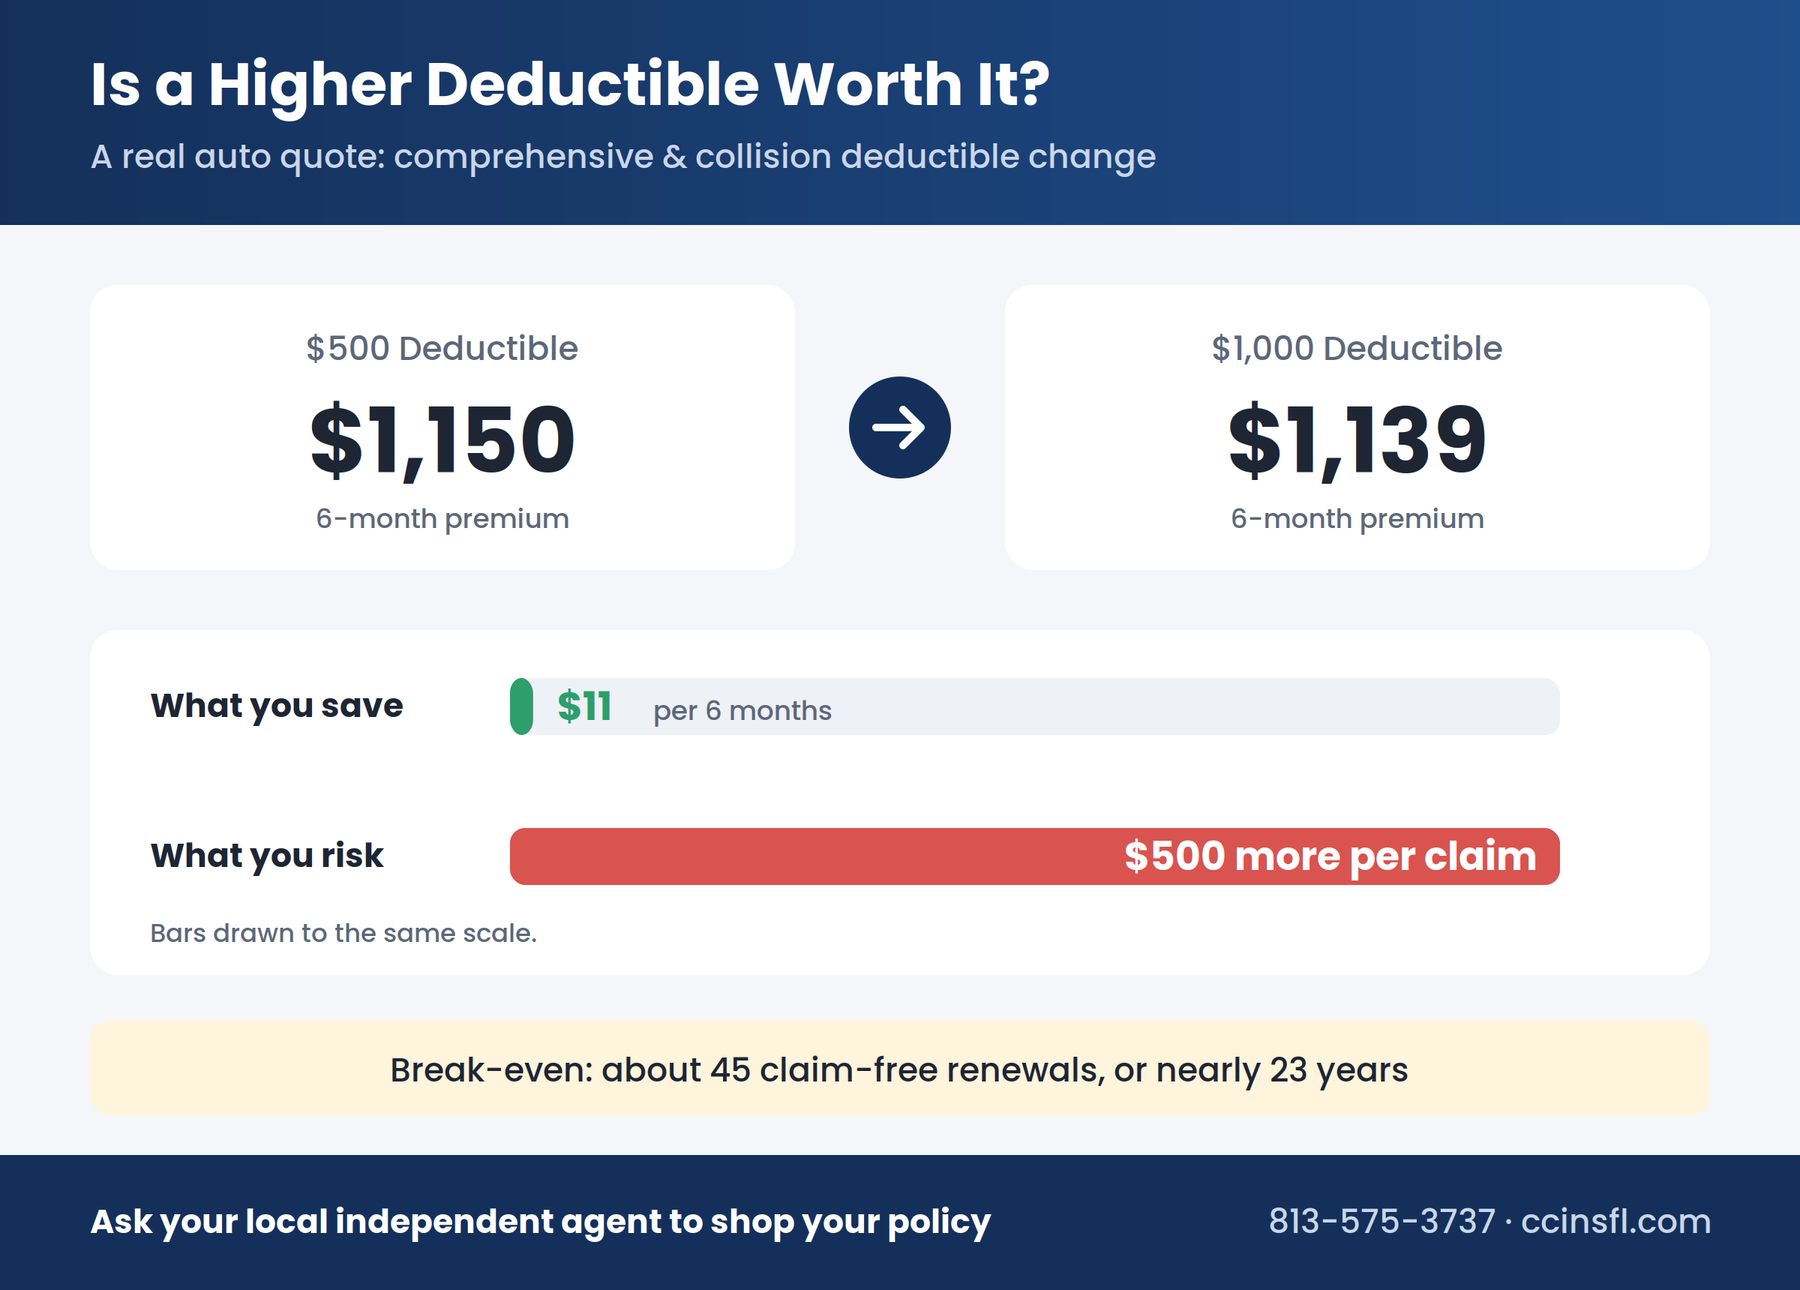
He asked what he would save by raising his comp and collision deductibles. He wanted to go from $500 to $1,000.
The answer surprised him. He would save just $11 every six months.
Think about that trade. He would take on $500 more risk for $11 in savings. One claim wipes out decades of those savings.
Most people would not make that bet if they saw the numbers first.
Why It Rarely Pays to Raise Your Car Insurance Deductible
Your deductible only applies to comprehensive and collision coverage. Those are just part of your total premium.
Liability coverage often makes up the biggest share of your bill. Your deductible does not touch it at all.
Many collision claims cost thousands to repair. On those claims, an extra $500 deductible barely changes what the insurer pays.
So the discount is often small. It can be even smaller on older or lower-value vehicles.
Before you raise your car insurance deductible, ask for the real numbers. Then ask yourself one question. Could you comfortably pay the higher amount tomorrow?
The Best Way to Lower Your Auto Insurance
The biggest savings usually come from shopping your policy. That is where an independent agent shines.
A captive agent can only offer one company. An independent agent works with many carriers. We compare them side by side for you.
One phone call can get you multiple quotes. You do not have to fill out form after form.
Bundle Your Home and Auto
Bundling is one of the most reliable discounts available. Many carriers reward you for placing home and auto together.
The savings can show up on both policies. You also get one point of contact for everything.
If your home and auto are with different companies, it is worth a look. We can quote them together and show you the difference.
What About Telematics and Usage-Based Insurance?
Many carriers now offer telematics programs. You may hear them called usage-based insurance.
These programs track how you drive. Most use a phone app or a small device in your car.
They often look at things like:
- Hard braking and fast acceleration
- Speed compared to posted limits
- Phone use while driving
- Late-night driving
- Total miles driven
Safe, low-mileage drivers can earn a real discount. For some people, it is a great fit.
But there is a catch. With some carriers, risky driving habits can raise your rate. A program meant to save you money could cost you more.
Every carrier’s program works a little differently. We can walk you through the details before you enroll.
The Bottom Line
Many people raise their car insurance deductible to save money. It is rarely the best way to do it.
In our client’s case, $11 was not worth $500 of extra risk. Your numbers may differ, so it pays to check.
Shopping your account and bundling usually do far more. Telematics can help too, if it fits your driving.
Let Us Shop Your Policy for You
We are your local independent insurance agency. We work for you, not for one insurance company.
We will compare carriers, look for bundle savings, and show you real numbers. Then you decide what makes sense.
More information can be found here: https://www.myfloridacfo.com/division/consumers/understanding-insurance/guides
Contact us today for a free policy review. Call our office, stop by, or send us a message. We are happy to help.
Phone: 813-575-3737
Email: Jeff@ccinsfl.com
Office: 4538C West Village Drive, Tampa, FL 33624
Website: www.ccinsfl.com