
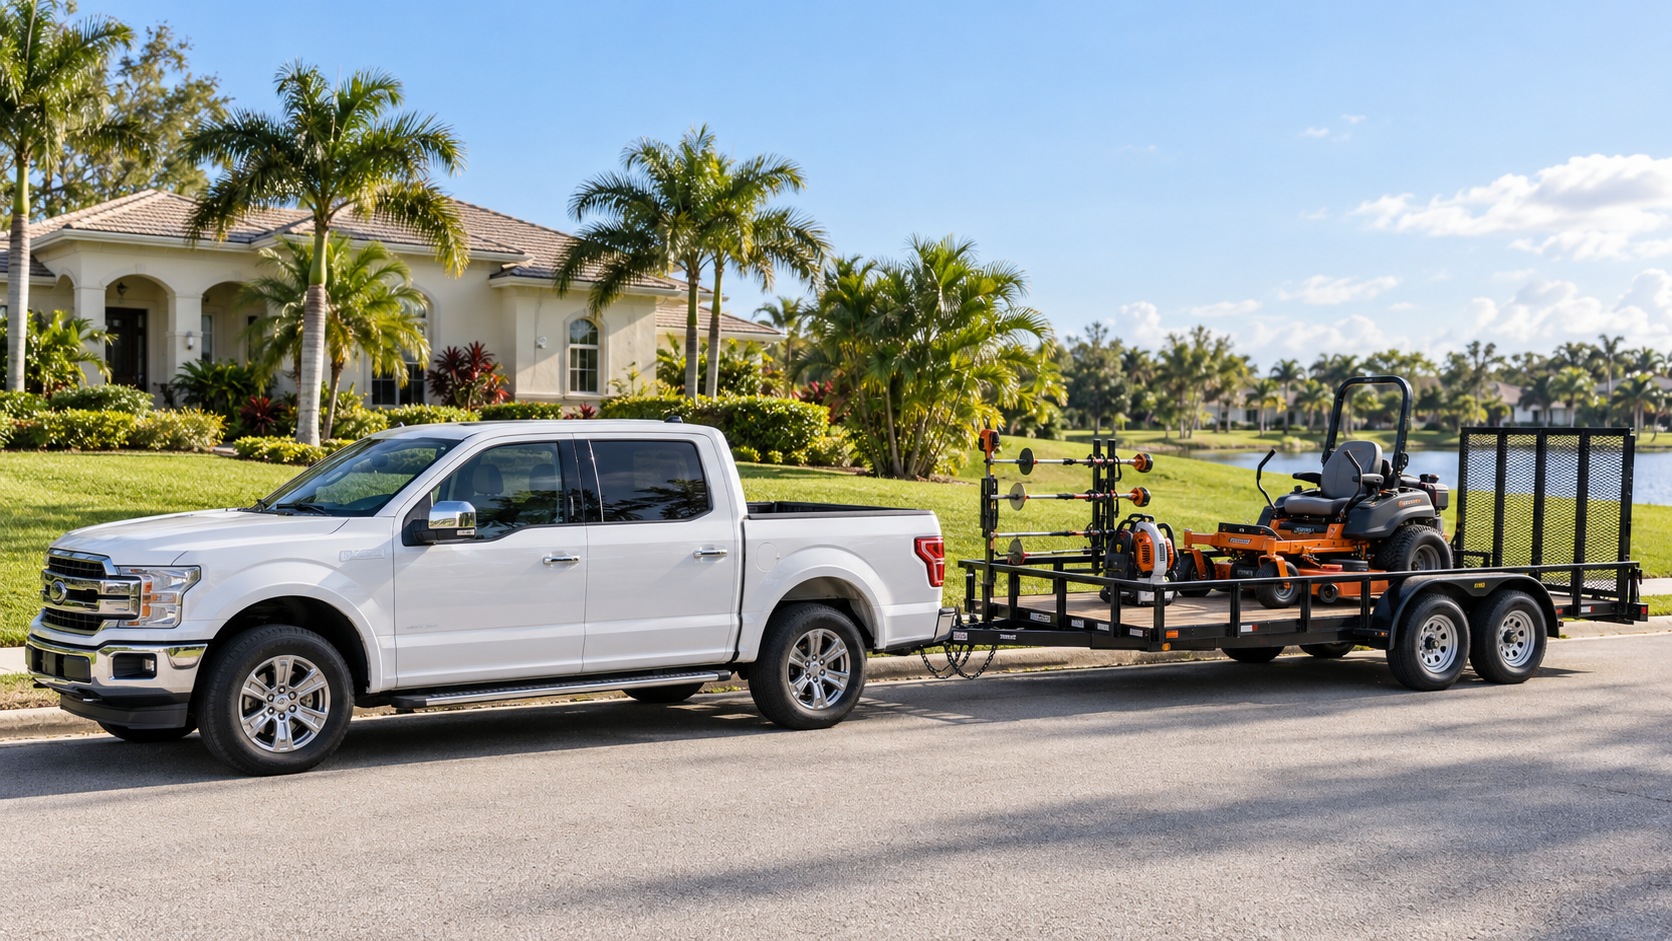
You’ve got a truck, a trailer, and a crew that starts at sunrise. Your personal auto policy might seem like enough, but for a landscaping business it leaves gaps that can cost you the whole company.
1. Personal auto policies often exclude business use
Many personal auto policies limit or deny coverage when the vehicle is used for business. Hauling mowers, trimmers, mulch, and a crew to job sites is business use. If you have an accident on the way to a client’s property, your insurer may deny the claim, and you’d be paying out of pocket.
2. Your auto policy doesn’t cover your equipment
Mowers, blowers, trimmers, and tools are expensive, and they’re often stored in open trailers. Auto insurance doesn’t cover equipment theft or damage. Inland marine (equipment) coverage protects your tools whether they’re on the trailer, at a job site, or in storage.
3. It doesn’t cover damage you cause on the job
A flying rock cracks a client’s window. A trimmer slices through an irrigation line. An employee damages a customer’s car in the driveway. None of these are auto claims. They fall under general liability insurance, which many clients and HOAs require before they’ll hire you.
4. Employees add risk your auto policy ignores
If a crew member is injured on the job, your auto policy won’t pay medical bills or lost wages. Depending on your number of employees and the type of work you do, workers’ compensation may be required in Florida, and it protects you from lawsuits after a workplace injury.
5. Chemicals and pesticides need their own protection
If you apply fertilizer, herbicides, or pesticides, standard policies often exclude pollution-related claims. Ask about pollution liability or a pesticide application endorsement so one drift complaint doesn’t become a lawsuit.
6. Employee and hired drivers create hidden exposure
When employees drive company vehicles, or use their own cars for supply runs, you can be held responsible. Commercial auto with hired and non-owned auto coverage helps protect you in those situations.
7. Florida weather is part of the job
Storms, hurricanes, and flooding can damage equipment and halt revenue. The right coverage package helps you recover faster.
What a well-protected landscape business typically carries
- Commercial auto insurance
- General liability
- Inland marine (tools and equipment)
- Workers’ compensation
- Pollution or pesticide liability, if applicable
- Commercial umbrella for extra limits
Every business is different, so the right mix depends on your crew size, equipment, and services.
Not sure where you stand? Let’s review it together.
C & C Insurance Solutions
4538C West Village Drive, Tampa, FL 33624
📞 813-575-3737
✉️ Jeff@ccinsfl.com
🌐 www.ccinsfl.com
This content is for general informational purposes only and does not alter or replace the terms of any insurance policy. Coverage availability and requirements vary.