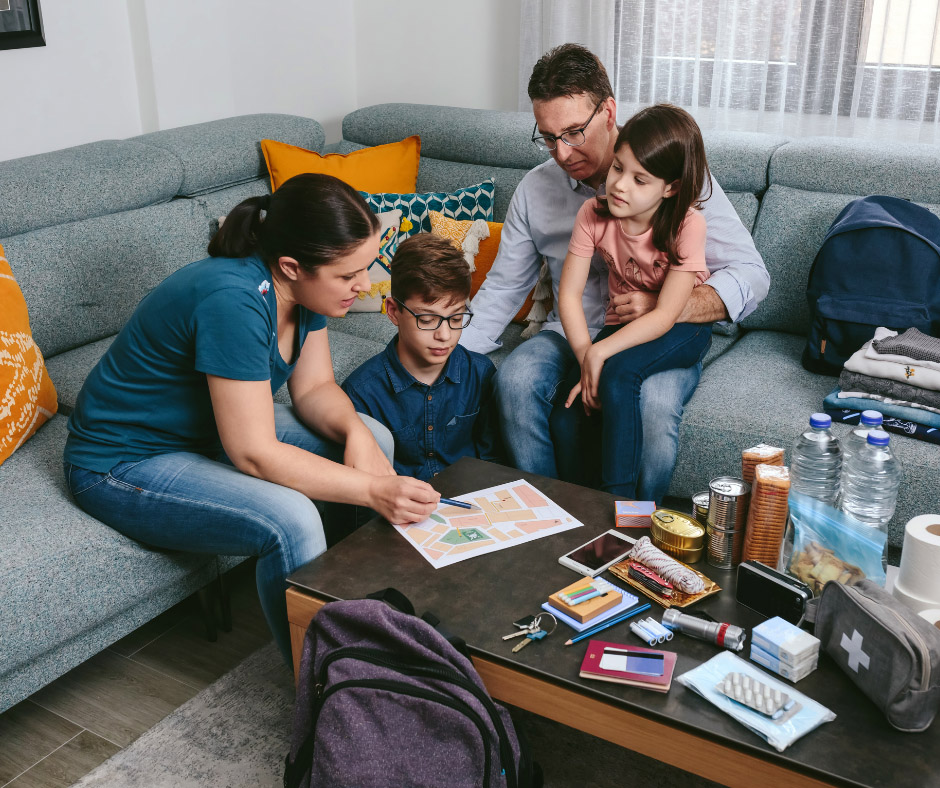
September brings peak severe weather risks across the country, aligning with National Preparedness Month and the high point of Atlantic hurricane season. Late-summer coastal storms, inland flash floods, and sudden severe wind events pose serious threats to residential and commercial properties alike. Reviewing your risk profile and insurance coverage now—before a storm enters the forecast—can make the difference between a smooth recovery and devastating out-of-pocket losses.
The Flood Insurance Gap The single biggest misconception among property owners is that standard insurance policies cover flood damage.
- Homeowners & Commercial Property Policies: Typically cover windstorm, hail, fallen trees, and water damage caused by rain entering through a storm-damaged roof or window.
- What They Exclude: Any water that touches the ground before entering a structure—such as rising rivers, coastal storm surges, or overflowing storm drains—is categorized as flooding and strictly excluded.
- The Solution: Flood protection requires a separate policy through the National Flood Insurance Program (NFIP) or private flood insurers. Keep in mind that flood policies usually carry a 30-day waiting period before coverage takes effect.
Business Continuity & Property Protection For business owners, physical damage from a storm is only half the battle. Extended power outages and structural repairs can shut down operations for weeks, causing severe income loss.
- Business Interruption Coverage: This critical endorsement reimburses lost net income and ongoing fixed expenses (like payroll and rent) if your business is forced to close due to a covered property loss.
- Utility Service Interruption: Standard business interruption often excludes off-site utility failures. Adding a utility endorsement protects your revenue if power or municipal water grids go down off-premises.
Pre-Storm Inspection Checklist
- Clear gutters, downspouts, and outdoor drains to prevent water backup.
- Trim dead tree branches overhang rooflines or parking areas.
- Inspect roof seals, flashing, and window caulking for gaps.
- Elevate inventory, electronics, and vital paper records off basement and ground floors.
- Digitally back up critical business data, operational files, and insurance documents to a secure cloud server.
- Audit your current property policy limits to ensure rebuilding costs reflect recent inflation and materials pricing.
Secure Your Protection Today Once a named storm or hurricane warning is issued, insurance carriers place binding restrictions that prevent adding or increasing coverage limits. Contact our agency this week for a comprehensive property and flood risk review to keep your home or business fully protected this fall.